High-net-worth individuals face a different set of investment challenges than the average investor. Larger corpus, complex tax exposure, multiple income sources and long-term legacy goals all demand a more deliberate approach. A well-structured HNI investment strategy is not about chasing the highest returns. It is about building a framework that balances growth, risk, liquidity and tax efficiency over decades, not quarters.
In India, an HNI is typically defined as someone with investable assets above ₹5 crore, while an Ultra HNI (UHNI) usually holds assets exceeding ₹25 crore. As this wealth grows, so does the complexity of managing it. Therefore, HNIs need more than a mutual fund SIP or a fixed deposit. They need a structured, risk-adjusted plan that accounts for every asset class, every tax bracket and every life goal.
This guide breaks down the core pillars of a sound HNI investment strategy, the questions every wealthy investor should ask before deploying capital, and the tax-efficient structures that protect long-term wealth.
Why HNIs Need a Different Investment Approach
Most retail investors focus on a handful of mutual funds and fixed deposits. However, HNIs typically manage wealth across multiple asset classes, business interests and geographies. This complexity changes the entire decision-making process, much the way organic traffic strategies for a growing SaaS business differ sharply from those of a small local shop.
A few reasons why a standard investment plan does not work for HNIs:
- Larger capital means concentration risk becomes a real threat
- Tax slabs and surcharge rates are significantly higher
- Liquidity needs often coexist with long-term illiquid holdings like real estate or business equity
- Legacy and succession planning become unavoidable considerations
- Access to alternative investments opens opportunities unavailable to smaller investors
Consequently, an effective HNI investment strategy must be built around structure and discipline, not around chasing the latest market trend.
The Five Questions Every HNI Should Ask Before a Large Investment
Before committing significant capital, disciplined investors pause and ask a structured set of questions. These questions prevent emotional decision-making and keep every large investment aligned with the broader portfolio.
1. What risk am I actually taking?
Every investment carries risk beyond the return figure on the brochure. Look at volatility, drawdown history and downside deviation. Understanding these metrics helps you gauge how an asset behaves when markets turn volatile, not just when they are rising.
2. How has it performed across full market cycles?
One-year returns can be misleading. Instead, evaluate rolling returns across bull markets, bear markets and sideways phases. This reveals consistency, which matters far more than a single strong year.
3. How does it fit into my overall asset allocation?
No investment should be evaluated in isolation. Ask whether it adds genuine diversification or simply duplicates an exposure you already hold elsewhere in the portfolio.
4. What is the acceptable downside scenario?
Every investment has a worst-case outcome. Knowing that number in advance, and confirming it fits within your risk capacity, prevents panic-driven exits during a downturn.
5. How does this affect liquidity, tax and long-term goals?
A high-performing asset can still be the wrong choice if it locks up capital you need soon, or creates an unplanned tax event.
These five questions form the foundation of a disciplined HNI investment strategy, shifting decisions away from impulse and toward structured evaluation.
Core Pillars of an Effective HNI Investment Strategy
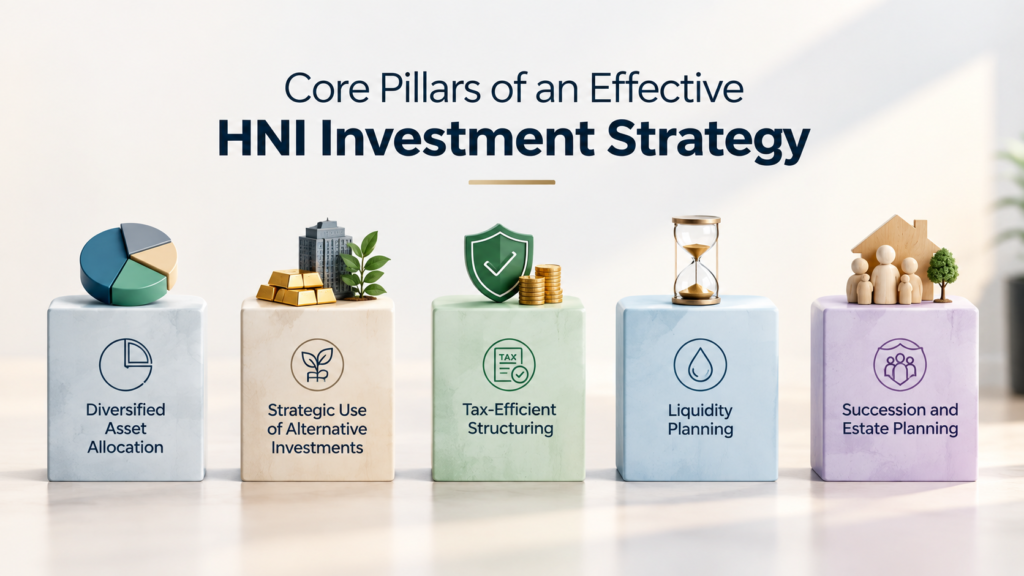
1. Diversified Asset Allocation
Diversification for HNIs goes well beyond splitting money between equity and debt. A mature portfolio typically spans listed equities, fixed income, real estate, private equity, structured credit and cash equivalents. Each asset class plays a distinct role, and no single class should dominate unless deliberately chosen.
2. Strategic Use of Alternative Investments
Alternative Investment Funds (AIFs), private equity, venture capital and structured credit have become central to modern wealth planning. Rather than replacing traditional holdings, alternatives complement equities and fixed income by offering exposure to different return drivers.
In India, AIFs are regulated by SEBI across separate categories, each covering a distinct investment approach. The objective of adding alternatives is not to chase higher returns alone. Instead, it is to reduce dependence on a single market or asset class.
Before adding any alternative investment, HNIs should evaluate:
- Liquidity and lock-in periods
- Fee structure and expense ratios
- Fund manager track record
- Concentration and leverage risk
- Tax treatment of gains
There is no fixed percentage that every HNI should allocate to alternatives. The right allocation depends on liquidity needs, existing exposures, and overall risk appetite.
3. Tax-Efficient Structuring
High tax outgo is one of the biggest threats to long-term wealth accumulation. Consequently, tax planning is not optional for HNIs; it is a core component of the investment strategy itself, and most investors rely on accounting and tax advisory practices to navigate it correctly.
Some commonly used tax-efficient approaches include:
- Long-term capital gains planning – Holding equity and debt instruments long enough to benefit from favourable LTCG tax treatment
- HUF (Hindu Undivided Family) structuring – Splitting income across a separate tax entity where applicable
- Family trusts – Consolidating assets for smoother succession and potential tax efficiency
- NPS and other retirement-linked instruments – Using available deductions strategically
- GIFT City and offshore structures – For HNIs with international income or investment needs
- Systematic tax-loss harvesting – Offsetting gains with realised losses within the same financial year
Because tax laws change frequently, HNIs should review their structuring at least once a year with a qualified advisor.
4. Liquidity Planning
Wealthy investors often assume liquidity is not a concern because of the size of their portfolio. However, illiquid assets like real estate, unlisted shares or long-lock-in AIFs can create real cash-flow stress during emergencies or planned expenditures. This is similar to how borrowers rely on mortgage and lending advisors to structure financing around cash-flow timing rather than convenience alone.
A sound HNI investment strategy always maintains a liquidity buffer, separate from long-term illiquid allocations, so that near-term goals are never dependent on selling assets at the wrong time.
5. Succession and Estate Planning
Wealth transfer is often the most neglected part of an HNI investment strategy. Without a clear will, trust structure or nomination framework, even a well-built portfolio can face disputes and delays. Many families work alongside estate planning law firms to formalise this process early, rather than leaving it until a crisis forces the issue.
Building succession planning into the strategy from the start protects both the capital and the family relationships around it.
Common Mistakes HNIs Make With Their Portfolios
Even sophisticated investors fall into avoidable traps. Some of the most frequent mistakes include:
- Chasing recent top-performing funds without checking long-term consistency
- Over-concentrating in real estate or a single business
- Ignoring the tax impact of an otherwise attractive investment
- Treating alternative investments as a status symbol rather than a portfolio tool
- Delaying estate and succession planning until it becomes urgent
- Reviewing the portfolio only during market downturns, instead of on a regular schedule
Avoiding these mistakes requires ongoing discipline rather than a one-time plan. An HNI investment strategy is a living framework that needs periodic rebalancing as goals, tax laws and market conditions evolve.
Building Your HNI Investment Strategy: A Practical Checklist
- Define clear short-term, medium-term and long-term goals
- Set a target asset allocation across equity, debt, real estate and alternatives
- Build a liquidity reserve before locking capital into illiquid assets
- Review tax structuring annually with a qualified advisor
- Evaluate every large investment against the five questions covered earlier
- Rebalance the portfolio periodically, not just during volatility
- Put a succession and estate plan in writing
How SurgeAIO can help in terms of SEO
Wealth management firms, family offices and financial advisory practices that serve HNIs face the same challenge as their clients: staying visible in a competitive, fast-changing landscape. Just as an HNI investment strategy needs structure and consistency, so does a firm’s digital presence.
For advisory businesses working with high-net-worth clients, ranking for the right search terms is essential to earning trust before a prospect ever picks up the phone. SurgeAIO helps fintech and wealth management firms strengthen their organic visibility so that high-intent prospects find them first. Beyond traditional search, SurgeAIO also helps firms understand how to rank in AI Overviews, a growing channel where prospective HNI clients now search for advisory guidance.
For firms unsure whether it’s the right time to invest in organic growth, understanding the fundamentals of hiring an SEO company is a useful first step. And once a strategy is live, tracking content performance and monitoring AI visibility metrics ensures that every piece of content – much like every investment – is evaluated on real, measurable outcomes rather than assumptions.
Final Thoughts
A strong HNI investment strategy is built on structure, not speculation. It combines diversified asset allocation, disciplined risk evaluation, tax-efficient structuring and clear succession planning into one coherent framework. By asking the right questions before every large investment and reviewing the portfolio regularly, high-net-worth investors can protect what they have built while continuing to grow it with confidence.
Frequently Asked Questions
1. What is the minimum net worth to be considered an HNI in India?
In India, an individual is generally classified as an HNI with investable assets above ₹5 crore. Those exceeding ₹25 crore are typically referred to as Ultra HNIs (UHNIs).
2. How much of an HNI portfolio should go into alternative investments?
There is no universal percentage. The right allocation depends on liquidity needs, investment horizon, risk tolerance and existing exposure to similar assets, such as private business holdings.
3. Is real estate still a good part of an HNI investment strategy?
Real estate can offer diversification and stability, but it is illiquid. It works best as one component of a broader strategy rather than the dominant asset class.
4. How often should an HNI review their investment strategy?
At minimum, once a year. However, significant life events, tax law changes or major market shifts should trigger an earlier review of the overall HNI investment strategy.
5. Should HNIs manage their own portfolio or use a wealth manager?
Given the complexity of tax planning, alternative investments and succession structuring, most HNIs benefit from working with a qualified wealth manager or advisory team rather than managing everything independently.
