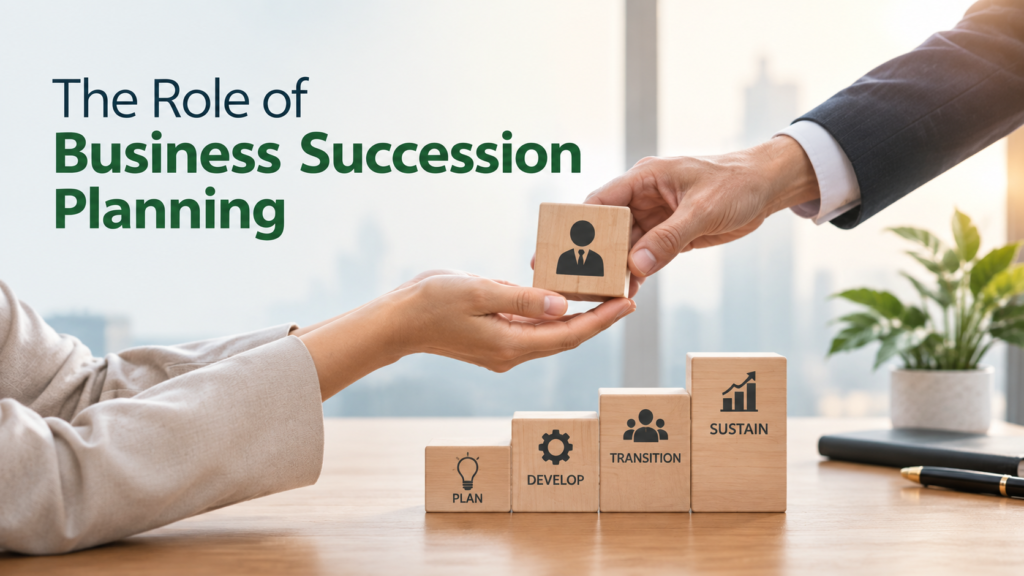
Every business owner eventually faces the same question: what happens to the company when I step away? Succession planning for business owners answers that question before it becomes a crisis. Without a clear plan, even thriving businesses can unravel during leadership transitions.
Succession planning for business owners is not just about retirement. It also covers unexpected events like illness, disability, or death. Consequently, owners who plan early protect both their company and their family’s financial future.
What Is Succession Planning for Business Owners?
Succession planning for business owners is the structured process of preparing a business for a change in leadership or ownership. It identifies who will take over, how the transition will happen, and how the outgoing owner will be compensated for their stake.
This process covers far more than naming a successor. It includes legal agreements, tax strategy, valuation, and often training the next generation of leadership. Therefore, treating succession planning as a one-time task rather than an ongoing strategy usually leads to gaps.
Why Succession Planning for Business Owners Matters
Many business owners delay succession planning because it feels distant or uncomfortable. However, waiting too long often limits options and increases risk for everyone involved.
Moreover, a business without a succession plan can lose significant value if leadership changes suddenly. Employees, customers, and lenders all look for stability, and uncertainty at the top erodes confidence quickly.
In addition, family-owned businesses face unique pressure. Without a documented plan, disagreements among heirs can disrupt operations or force an unplanned sale. Succession planning for business owners helps prevent these outcomes before they occur.
Common Mistakes Business Owners Make
Even experienced owners often mishandle succession planning. Recognizing these mistakes early can save significant time, money, and stress later.
- Waiting too long to start: Many owners begin planning only when retirement or health issues force the conversation.
- Failing to document a plan: Verbal intentions carry no legal weight and often create confusion among heirs or partners.
- Ignoring valuation: Without an accurate business valuation, buyouts and inheritances become guesswork.
- Overlooking tax consequences: Poorly structured transitions can trigger unnecessary capital gains or estate taxes.
- Not preparing successors: Handing over leadership without proper training often destabilizes operations.
Avoiding these mistakes requires a proactive, well-documented approach rather than reactive decision-making.
Core Elements of Effective Succession Planning
1. Define Clear Goals
Succession planning for business owners starts with clarity about personal and business goals. Owners should decide whether they want to pass the company to family, sell to a partner, or exit entirely to a third party.
These goals shape every decision that follows, from valuation methods to leadership training timelines. Therefore, defining them early prevents wasted effort later.
2. Choose and Prepare a Successor
Selecting the right successor is one of the most critical steps in succession planning for business owners. This person may be a family member, a business partner, or a trusted employee.
Once chosen, successors need real preparation. Mentorship, gradual responsibility increases, and formal training all help ensure a smoother transition when leadership officially changes.
3. Get an Accurate Business Valuation
A professional valuation establishes the true worth of the business, which is essential for fair buyouts, tax planning, and negotiations. Without this figure, succession planning for business owners becomes guesswork.
Valuations should be updated periodically, since business worth can shift significantly due to market conditions, revenue changes, or industry trends.
4. Build a Formal Legal Structure
Buy-sell agreements, shareholder agreements, and trusts all provide the legal framework needed for a smooth transition. These documents specify exactly how ownership transfers and under what conditions.
Without formal agreements, disputes often arise between remaining owners, family members, or successors. Consequently, legal documentation should never be treated as optional.
5. Align Wealth and Investment Strategy
Many business owners hold most of their net worth inside the company itself. As succession approaches, aligning that wealth with a broader financial plan becomes essential.
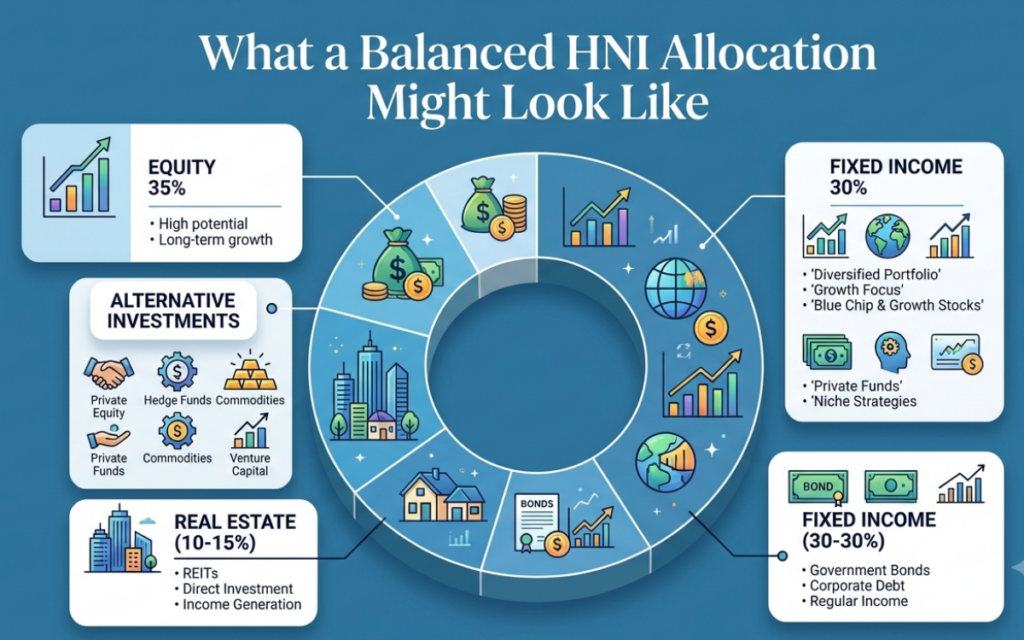
This often involves a thoughtful HNI investment strategy that accounts for the liquidity event created by selling or transferring the business, along with the owner’s post-transition lifestyle needs.
6. Diversify Beyond the Business
Owners who have most of their wealth tied up in one company face significant concentration risk. Careful asset allocation for HNI investors helps spread that risk across multiple asset classes as the transition unfolds.
Equally important is genuine portfolio diversification for HNI investors, which protects proceeds from the business sale or transfer from being overly dependent on a single investment.
7. Coordinate Ongoing Portfolio Management
Once succession is underway, proceeds and remaining assets require active oversight. Professional portfolio management for HNI households ensures that wealth generated through succession is managed cohesively rather than in scattered accounts.
This coordination becomes especially important when multiple family members or stakeholders are involved in the outcome.
8. Protect What Has Been Built
Succession planning for business owners should always include a wealth protection component. Sound wealth preservation strategies safeguard the value created by decades of work from taxes, inflation, and poor decision-making.
Ultimately, genuine wealth preservation ensures that the financial rewards of building a business actually last across the owner’s retirement and beyond.
9. Communicate the Plan Clearly
Transparency matters just as much as legal structure. Owners should communicate their succession plan to key stakeholders, including family members, partners, and senior employees, well before the transition occurs.
Clear communication reduces uncertainty and helps everyone involved prepare for their role in the company’s future.
Timing Your Succession Plan
Succession planning for business owners works best when it starts five to ten years before an expected transition. This timeline allows enough room to develop successors, address tax implications, and adjust strategy as circumstances change.
- Begin conversations with potential successors early, even informally.
- Schedule a professional valuation every two to three years.
- Review legal agreements annually to ensure they still reflect current goals.
- Build a financial plan that accounts for life after the transition.
- Revisit the entire plan after major life or business events.
The Role of Professional Advisors
Succession planning for business owners rarely succeeds without coordinated professional guidance. Attorneys, accountants, and financial advisors each play a distinct role in building a workable plan.
Furthermore, advisors help business owners avoid blind spots that are easy to miss when handling succession internally. Because so much value is often tied up in a single company, getting this guidance right can significantly affect long-term outcomes.
How SurgeAIO can help in terms of SEO
Advisory firms that specialize in succession planning need strong online visibility to reach business owners actively searching for guidance. Many owners begin their research online long before contacting a professional.
SurgeAIO helps advisory and financial planning firms build that visibility through SEO strategies suited to complex, trust-driven services. Because succession and wealth planning overlap with financial services broadly, partnering with a specialized fintech SEO agency often outperforms generic marketing approaches.
Firms new to organic search benefit from understanding SEO lead generation — a consistent pipeline of business owners searching for succession guidance, rather than relying solely on referrals or cold outreach.
Since succession planning frequently involves coordination with attorneys, reviewing SEO lead attribution for law firms can reveal how referral partnerships and search visibility work together to generate qualified leads across both professions.
Final Thoughts
Succession planning for business owners protects far more than a company’s operations. It safeguards years of hard work, financial security, and the livelihoods of everyone connected to the business. Owners who start early, document their plans, and align their personal wealth strategy alongside the transition are best positioned for a smooth outcome.
As more business owners approach retirement in the coming years, proactive succession planning will separate companies that thrive through transition from those that struggle. Starting the conversation today is the first step toward protecting tomorrow.
Frequently Asked Questions
What is the difference between succession planning and an exit strategy?
Succession planning focuses specifically on transferring leadership and ownership, often to a successor within the business. An exit strategy is broader and can include selling to an outside party rather than transitioning internally.
When should business owners start succession planning?
Most advisors recommend starting five to ten years before an expected transition. This timeline allows enough time to prepare successors, address tax issues, and adjust the plan as needed.
Does succession planning matter for small businesses?
Yes. Even small companies benefit from a documented plan. Without one, an unexpected event can leave employees, customers, and family members without clear direction.
How does business valuation factor into succession planning?
An accurate valuation ensures fair buyouts, informs tax strategy, and provides a realistic baseline for negotiations between outgoing and incoming owners.
What happens if a business owner has no succession plan?
Without a plan, the business may face forced sales, legal disputes, or operational disruption if the owner becomes unable to lead unexpectedly.
Can succession planning include multiple successors?
Absolutely. Many businesses transition leadership to a team rather than a single person, particularly when family members or long-term partners share responsibility.