Trillions of dollars are shifting hands as older generations pass wealth to their children and grandchildren. This shift, known as intergenerational wealth transfer, is reshaping how families plan, invest, and think about their legacy. Without a clear strategy, however, much of that wealth can be lost to taxes, poor planning, or family disputes.
Understanding intergenerational wealth transfer is no longer optional for families with meaningful assets. It requires coordination between estate planning, tax strategy, and investment management. Consequently, families who start early tend to preserve significantly more value than those who wait.
What Is Intergenerational Wealth Transfer?
Intergenerational wealth transfer describes the movement of assets, property, and financial resources from one generation to the next. It covers cash, investment portfolios, real estate, business ownership, and even non-financial assets like family values and financial discipline.
This process rarely happens all at once. Instead, it unfolds gradually through lifetime gifts, trusts, inheritances, and structured estate plans. Therefore, treating it as an ongoing strategy rather than a single event tends to produce better outcomes.
Why Intergenerational Wealth Transfer Deserves Attention Now
Several factors make intergenerational wealth transfer especially urgent today. Older generations control a large share of global assets, and many are entering the later stages of life. As a result, the window for thoughtful planning is narrowing.
Moreover, rising life expectancy means wealth often needs to stretch across three generations simultaneously. A grandparent, parent, and grandchild may all depend on the same financial resources at once, which adds real complexity to decision-making.
In addition, shifting tax rules and market volatility can erode inherited wealth quickly if there is no strategy behind it. Families that ignore intergenerational wealth transfer planning often lose value they could have easily protected.
Common Mistakes Families Make
Even financially sophisticated families frequently mishandle intergenerational wealth transfer. Recognizing these mistakes early can prevent costly consequences later.
- Avoiding money conversations: Parents often hesitate to discuss finances openly, leaving heirs unprepared to manage what they inherit.
- Skipping formal documentation: Without a will or trust, state default laws decide how assets are divided, not the family’s actual wishes.
- Overlooking tax efficiency: Poorly timed transfers can trigger unnecessary estate, gift, or capital gains taxes.
- Ignoring business succession: Family businesses without a leadership plan often struggle or collapse after ownership changes hands.
- Underestimating heir preparation: Sudden wealth without financial education can overwhelm and mismanage inherited assets.
Avoiding these pitfalls requires more than a basic will. It requires an active, ongoing strategy involving several financial disciplines.
Core Strategies for a Successful Intergenerational Wealth Transfer
1. Build a Strong Estate Plan
A comprehensive estate plan forms the backbone of any intergenerational wealth transfer strategy. This typically includes a will, powers of attorney, healthcare directives, and one or more trusts depending on complexity.
Trusts offer particular flexibility. They can control the timing of distributions, shield assets from creditors, and reduce estate tax exposure. Consequently, many advisors recommend trust structures even for moderately sized estates.
2. Prioritize Wealth Preservation
Preserving wealth across generations requires more than saving money; it requires active protection against inflation, market downturns, and poor decision-making. Sound wealth preservation strategies typically combine diversified investments, insurance planning, and tax-efficient structures.
Families focused purely on growth sometimes overlook protection, which can undo decades of accumulated value. Therefore, balancing growth with genuine wealth preservation should be a core part of any long-term plan.
3. Align Investment Strategy with Family Goals
High-net-worth families often need a more sophisticated approach than standard retirement planning offers. A well-structured HNI investment strategy accounts for liquidity needs, multi-generational time horizons, and complex tax situations.
This typically involves close portfolio management for HNI households, where advisors coordinate across multiple accounts, entities, and family members rather than managing assets in isolation.
4. Diversify and Allocate Thoughtfully
Concentrated positions, whether in a family business or a single stock, create unnecessary risk for heirs. Careful asset allocation for HNI investors spreads risk across asset classes while still targeting long-term growth.
Equally important is genuine portfolio diversification, which protects the family’s wealth from being overly dependent on any single market, sector, or asset type.
5. Use Lifetime Gifting Strategically
Gifting assets during one’s lifetime can reduce the taxable estate while allowing heirs to benefit sooner. Annual exclusion limits allow individuals to gift set amounts per recipient without triggering gift tax.
However, gifting should never compromise the giver’s own financial security. Balancing generosity with personal retirement needs keeps the overall plan sustainable.
6. Communicate Openly Across Generations
Transparent conversations about money matter just as much as legal paperwork. Families who discuss expectations, values, and responsibilities tend to experience far fewer disputes during intergenerational wealth transfer.
Regular family meetings, even informal ones, help clarify intentions well before they become urgent. Ultimately, communication builds the trust needed for a smooth transition.
7. Prepare Heirs Financially
Passing on wealth without preparing heirs to manage it often backfires. Financial literacy covering budgeting, investing, and basic tax concepts should accompany any significant transfer.
Some families involve younger members in investment decisions years before assets actually change hands. This hands-on exposure builds confidence instead of overwhelming new heirs.
8. Revisit the Plan Regularly
Life circumstances change constantly. Marriages, births, divorces, and new tax laws can all affect an estate plan. Therefore, reviewing the intergenerational wealth transfer strategy every few years keeps it relevant and effective.
The Role of Business Succession Planning
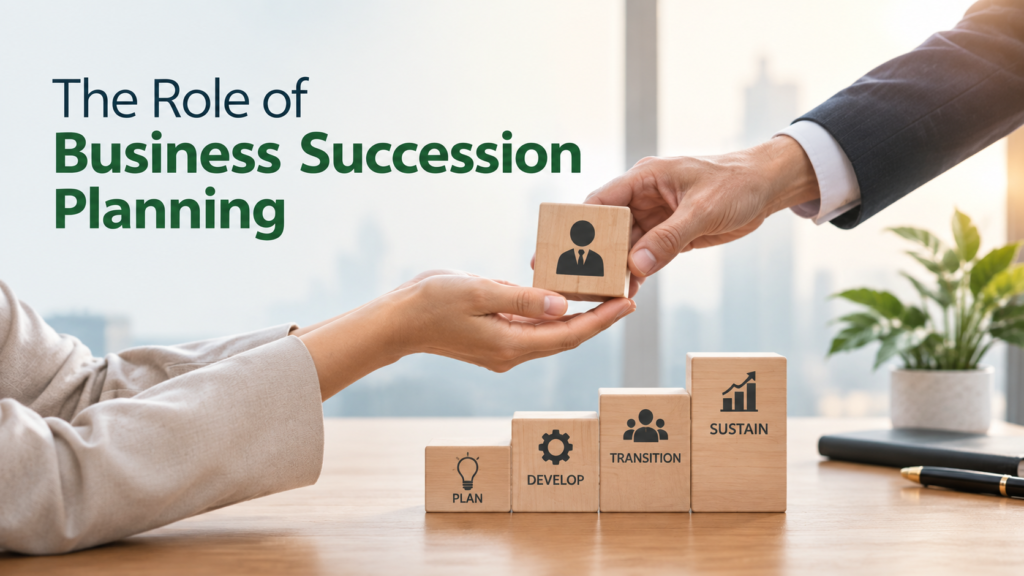
Family-owned businesses add real complexity to intergenerational wealth transfer. Succession planning should clarify who will lead the company, how ownership will be divided, and how heirs not involved in operations will be treated fairly.
Buy-sell agreements, professional valuations, and clear leadership timelines all help prevent disputes when a business represents a major share of the estate.
How Financial Advisors Support This Process
Advisors play a central role in guiding families through intergenerational wealth transfer. They coordinate estate attorneys, tax professionals, and investment managers to build one cohesive strategy rather than disconnected pieces.
Furthermore, advisors help translate complex legal and financial concepts into practical steps families can actually follow. Because so much wealth is expected to move over the coming decades, competition among advisory firms trying to reach these families is intensifying.
How SurgeAIO can help in terms of SEO
Financial advisory firms that want to serve families going through intergenerational wealth transfer need strong visibility online. Prospective clients research extensively before choosing an advisor, so ranking for the right search terms matters enormously.
SurgeAIO helps wealth management and advisory firms build that visibility with SEO tailored to complex, high-trust financial services. Because this niche demands accuracy and compliance-awareness, working with a specialized fintech SEO agency can make a measurable difference over generic marketing approaches.
Firms unfamiliar with how organic search actually generates business benefit from understanding SEO lead generation – a steady pipeline of prospects actively searching for guidance, rather than relying solely on referrals.
Since advisory firms frequently partner with estate attorneys, reviewing SEO lead attribution for law firms can also reveal how overlapping search traffic and referral partnerships influence lead quality across both professions.
Final Thoughts
Intergenerational wealth transfer is far more than moving money from one generation to the next. It involves protecting a family’s legacy through thoughtful estate planning, disciplined investing, and open communication. Families who start early, diversify wisely, and revisit their strategy regularly are best positioned to preserve what they have built.
As significant wealth continues shifting between generations in the years ahead, both families and the advisors who serve them have a genuine opportunity – provided they plan proactively rather than reactively.
Frequently Asked Questions
What is the difference between intergenerational wealth transfer and estate planning?
Estate planning is the legal process of documenting how assets will be distributed. Intergenerational wealth transfer is the broader, ongoing process of moving wealth, values, and financial knowledge between generations, of which estate planning is one component.
When should families start planning for intergenerational wealth transfer?
Ideally, planning should begin well before retirement. Starting early allows more time for tax-efficient gifting, trust structures, and honest family conversations, rather than rushed decisions during a crisis.
Does intergenerational wealth transfer planning matter for smaller estates?
Yes. While large fortunes attract headlines, even modest estates benefit from a clear plan. Avoiding probate delays, reducing taxes, and preventing disputes matter regardless of estate size.
How does investment strategy affect intergenerational wealth transfer outcomes?
A well-diversified, professionally managed portfolio protects wealth from concentrated risk and market volatility, which directly affects how much value actually reaches the next generation.
What role does communication play in a successful transfer?
Communication is often more important than the legal documents themselves. Families who discuss expectations openly tend to experience fewer disputes and better long-term outcomes.
Can a family business be part of an intergenerational wealth transfer plan?
Absolutely. Business succession planning, including leadership transition and fair treatment of all heirs, is a critical piece of preserving wealth tied up in a family enterprise.
